Key takeaways
- Omdia predicts a 120% CAGR for monthly AI-enriched data from 2023–2030, so vast amounts of new fiber are needed to interconnect data centers
- EXA Infrastructure and Ciena are speaking on an industry panel at ITW 2025 in May, with a drinks reception straight after
- The panel covers the state of the data center industry, the challenges facing DCI players, new strategies and innovations, and the future of DCI
- Google, Skanska and Green Mountain have all set up in Norway to take advantage of its near-100% renewable hydropower
- Near-term connectivity trends include 800Gb/s technology, managed fiber networks (MFN), and edge-to-core integration
Why fiber matters for the AI boom
Surging demand for AI is putting the data center industry in the spotlight. New locations, new industry players and new energy sources to power our AI future have all been making headlines.
But none of it can happen without a rather less headline-grabbing element: the fiber and connectivity that interconnect data centers together.
With Omdia predicting a 120% CAGR for monthly AI-enriched data from 2023–2030, vast amounts of new fiber are needed to ensure data centers can connect seamlessly—for AI training and inferencing, backup, restore, cloud services, and core-to-edge communications.
EXA and Ciena on the ITW 2025 panel
The future of DCI in the spotlight at ITW 2025
EXA Infrastructure, in collaboration with Ciena, are working at the forefront of the data center interconnect market, giving us deep insight into the many challenges—and opportunities—currently facing the various players, as well as new ways to address them.
At an industry panel session at ITW 2025 in May, we’ll discuss our experiences and learnings from the past year, as well as the trends we’re seeing in the market and our predictions for the future of DCI business opportunities.
The panel is on May 5th at 4.10pm in the Woodrow Wilson Room—and here’s just a flavour of the topics we’re looking forward to discussing.
Panel details
- ITW 2025 in May
- May 5th at 4.10pm
- Woodrow Wilson Room
- Drinks reception straight after the panel
Where is the data center industry heading?
- New sites, new power sources, new drivers: the state of the data center industry
First up is the huge amount of change afoot in the industry. There are geographical opportunities spurred by the need to find land and sustainable power, which is typically away from traditional urban areas. Google, Skanska and Green Mountain, for example, have all set up in Norway to take advantage of its near-100% renewable hydropower.
Data traffic is also growing steadily, and not just because of AI. More storage and processing is happening in the cloud than ever, and the proliferation of ‘smart everything’ is contributing to a huge increase in data from IoT sensors. Latency-critical applications, like autonomous driving are spurring the rollout of interconnected edge data centers, bringing compute assets closer to sources of data production and consumption.
There are clearly opportunities within the fast-evolving DCI ecosystem for service providers keen to capitalize on the demand for new fiber and related services. We’re hoping to discuss what those opportunities look like and how the wider industry can best respond to them.
What challenges do DCI players face?
- From cable cuts to changing regulations: challenges facing DCI players
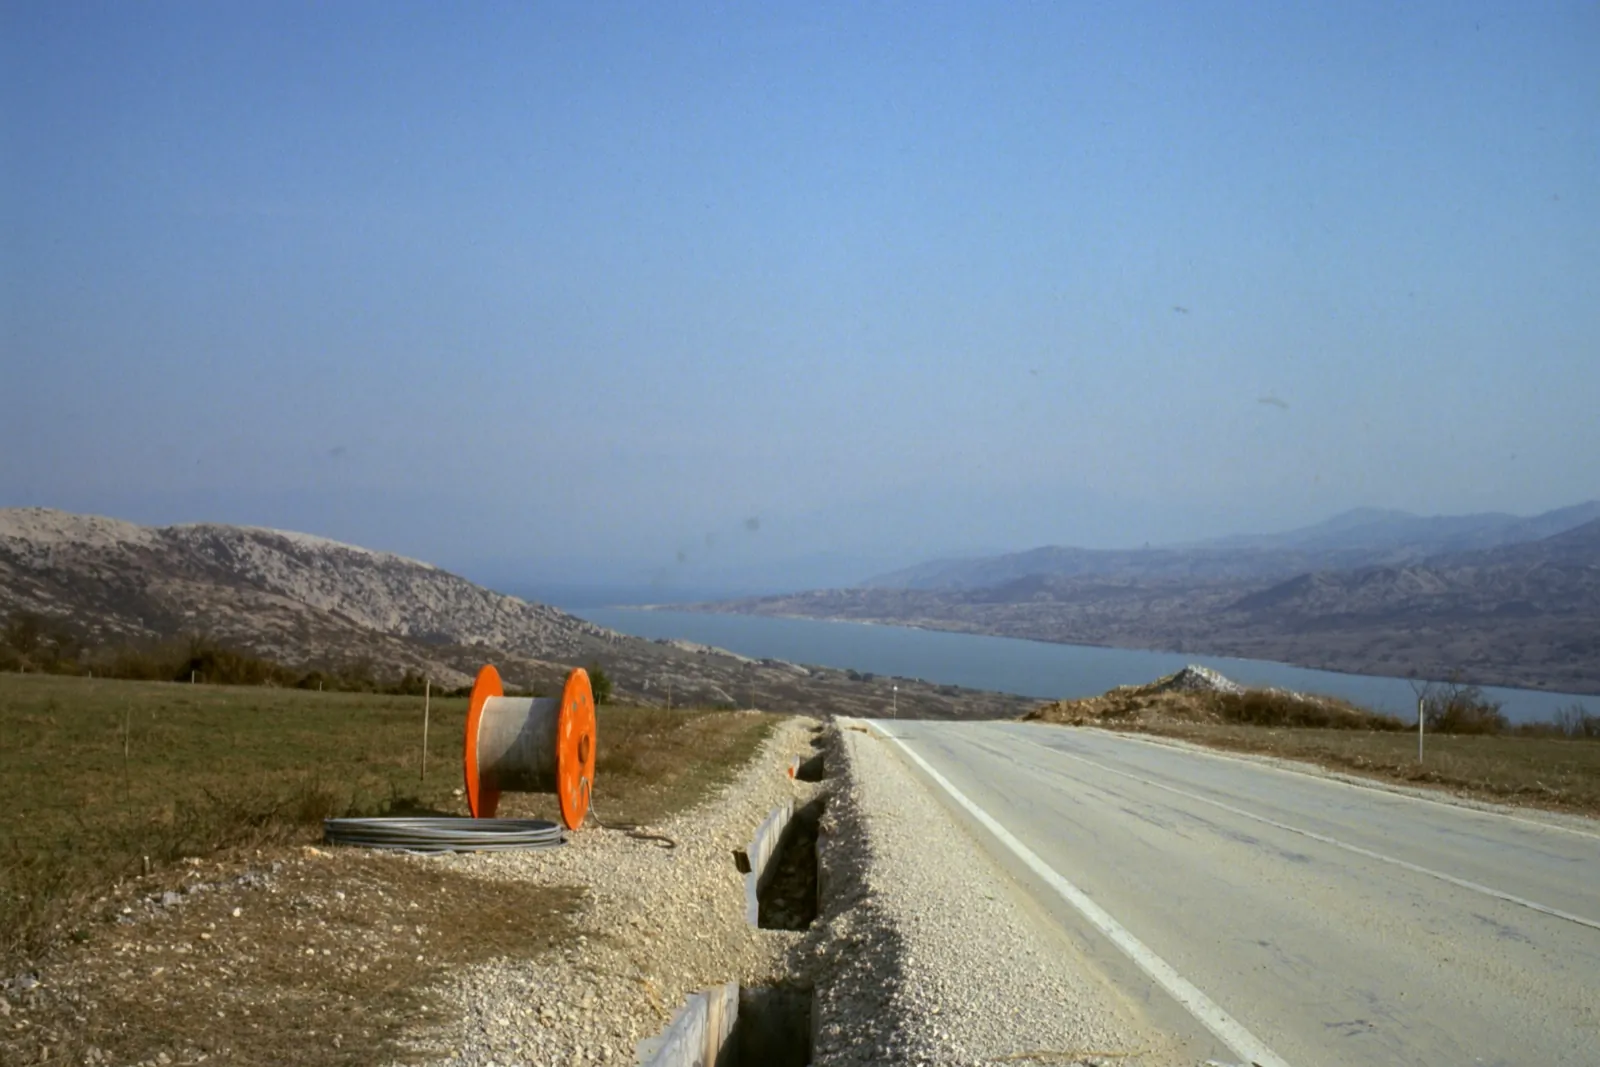
No one underestimates the complexities of data center interconnect. At our panel, we'll tackle key challenges in planning, building, managing, and scaling DCI across markets, from navigating difficult terrain to securing diverse routes and addressing geopolitical sensitivities.
Physical challenges go hand in hand with the often eye-watering expense of laying new fiber, the variable economics of connectivity across different regions, and the need to build a compelling business case for investment.
A third dimension is the regulatory environment, particularly for DCI spanning different jurisdictions, each with its own evolving regulations.
And we’ll also look at the challenges inherent in achieving and guaranteeing the required levels of network performance—particularly as an increased number of applications rely on ultra-low latency.
Which strategies and innovations are emerging?
- Problem-solving for a new era of DCI: latest strategies and innovations
The ever-evolving landscape of DCI presents new connectivity challenges, pushing our industry to continually innovate. With the rapid increase of core and edge data centers, we face numerous new problems—but also discover exciting solutions.
In this new era of DCI, we're eager to explore the latest strategies and innovations that have emerged recently. These include advances like the shift to route “quadversity” for assured low latency and the newest topologies for efficient global and local fabrics.
Another component to take into consideration is the evolution of Cable Landing Stations (CLS). With many now becoming “mini datacenters”, we’ll look at how this expanded computing capability is opening new dimensions in DCI.
We’ll also want to look at new commercial and funding models, new routes to ROI—especially in new locations—and new ways of collaborating to streamline deployments and operations.
What does the future of DCI look like?
- Looking ahead: The many exciting futures of data center interconnect
With AI services based on Large Language Models (LLMs) still in their infancy, along with latency-critical use cases like industrial automation and smart city infrastructure, it feels like we’re just at the start of a revolution in data center strategy and data center interconnect.
Those new use cases will drive further technological and commercial innovations, enabling fiber networks and service providers to keep pace with the evolving data center landscape.
From a connectivity point of view, we’re sure to be discussing near-term trends like 800Gb/s technology, managed fiber networks (MFN), and edge-to-core integration. And there may also be a chance to look future innovations like multi-rail, multi-core, and hollow core fibers.
Overall, we’ll look at how data centers are likely to continue to evolve in terms of geographical location, distribution of workloads ‘beyond four walls’, and the balance between core and edge.
These developments will require data center operators and telecommunications companies to work ever closer together—something we’re excited to see and support in the coming years.
See you in Maryland!
ITW is always great for bringing different ecosystem players together, and we hope the panel session will inspire some new conversations and collaborations.
If you’re planning to attend, we’d love to see you there. As well as the panel session, we’ll be hosting a drinks reception straight after the panel to further discuss the trends, challenges and opportunities we’ve outlined in this blog. Drop by and say hello!
https://www.internationaltelecomsweek.com/itw-agenda-2025/bespoke-panel-discussion
#EXAInfrastructure
#DataCenterInterconnect
#SubseaConnectivity
#FiberOpticTech
#GlobalNetworkInfrastructure